
Explore Your Financing Options
Every business is different — and so is every financing solution. Understanding what's available, what it costs, and what lenders look for helps you make smarter decisions for your business.
Finding the Right Fit
Financing options range from fast, flexible alternatives to long-term conventional loans and government-backed SBA programs. Each comes with different costs, repayment structures, collateral requirements, and qualification standards. This overview is designed to help you understand your options — not to promise approval or specific terms, which are always determined by individual lenders and programs.
- Alternative financing for businesses still building credit
- Conventional loans for established, lender-ready businesses
- SBA programs for the best rates and longest terms
Know Which Programs You Qualify For Before You Apply
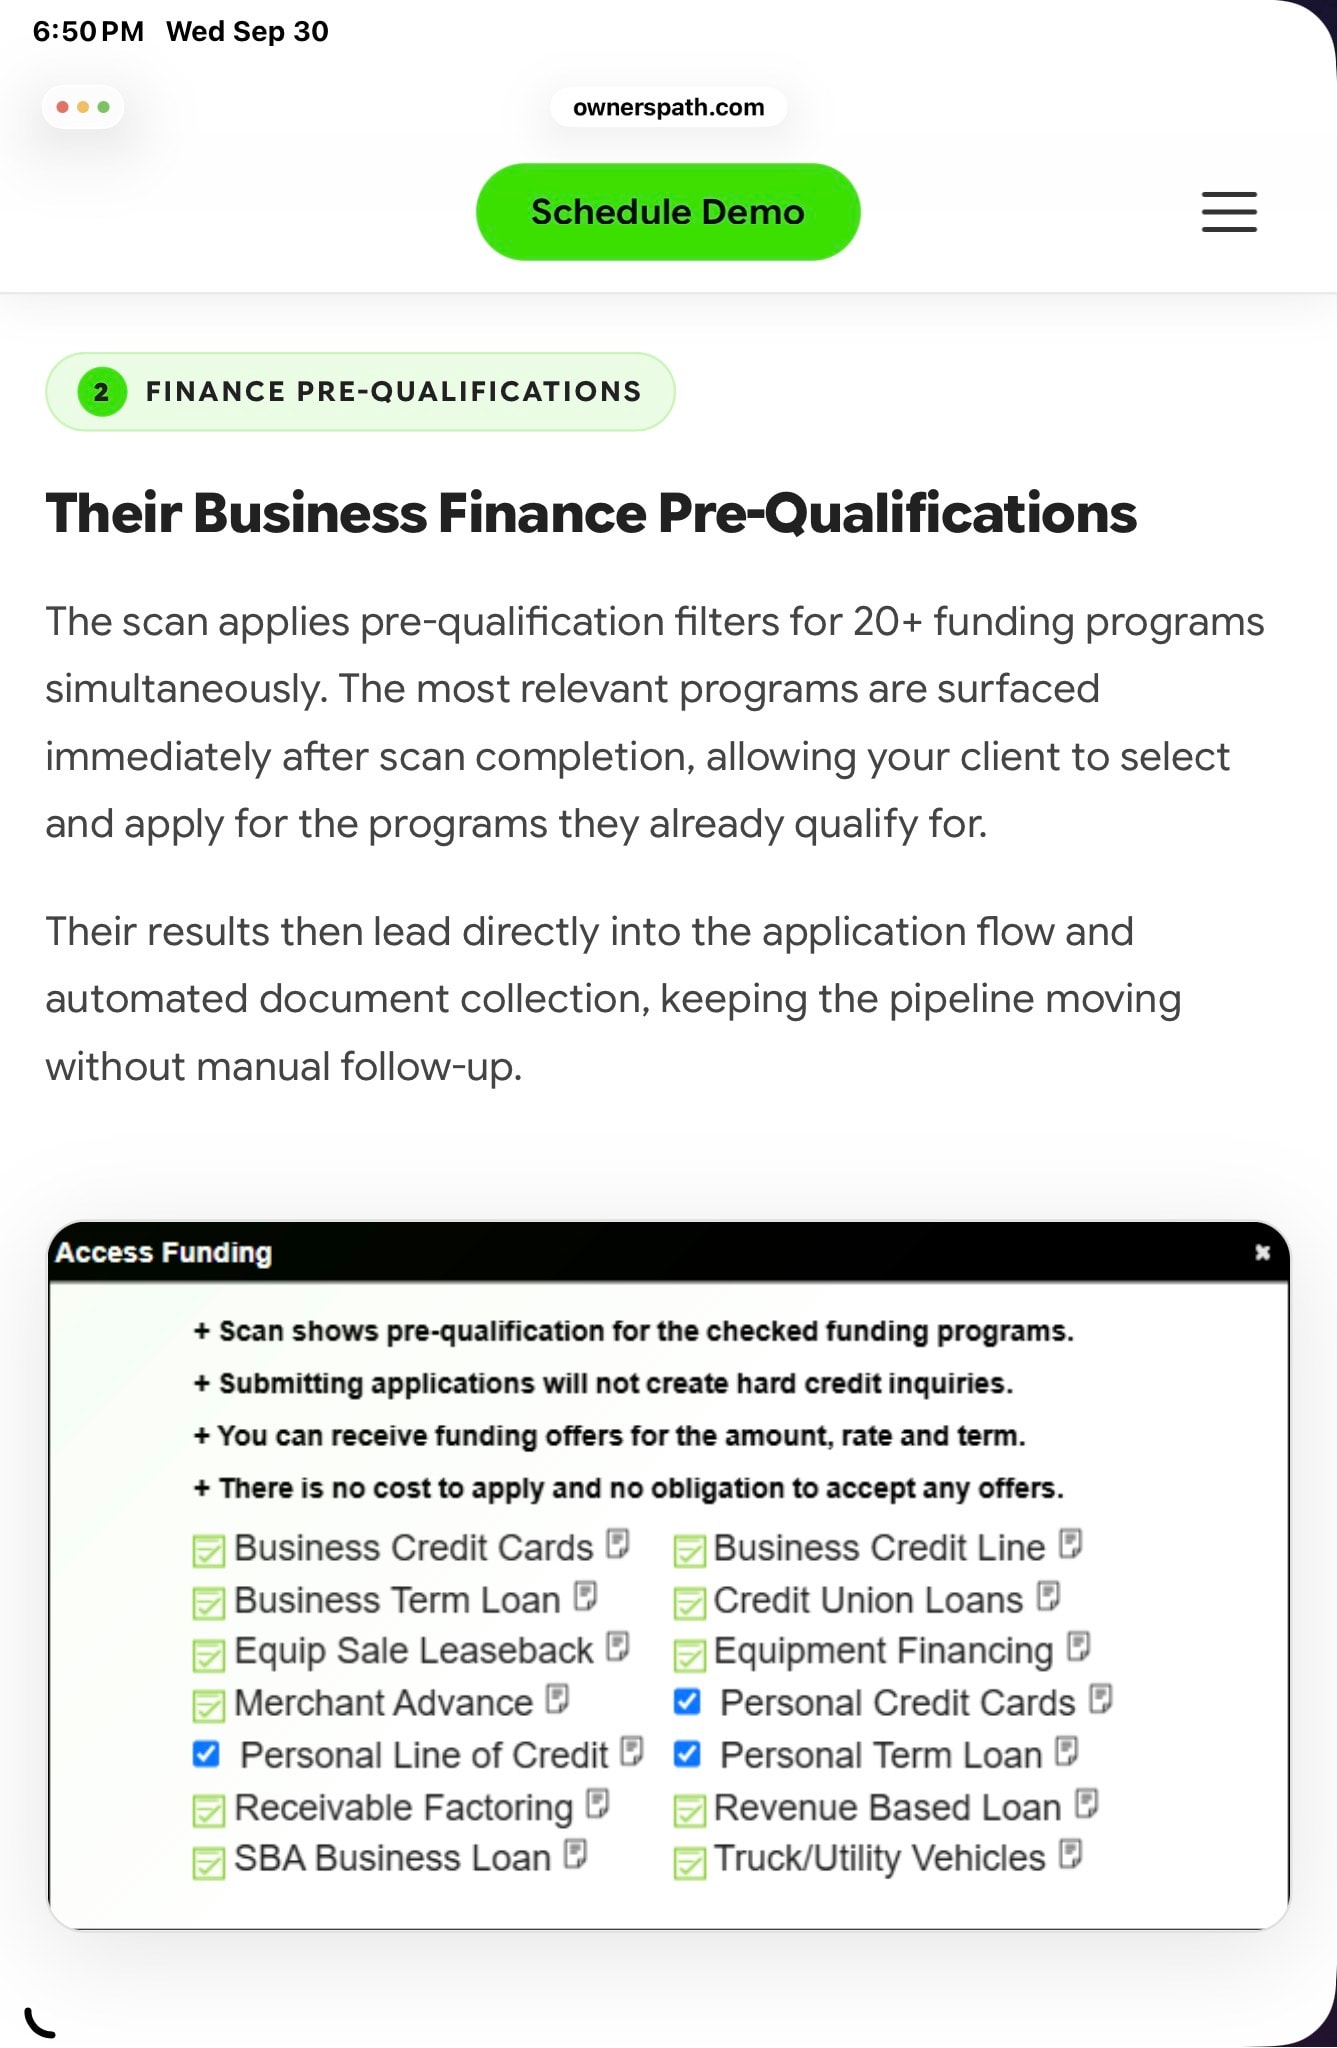
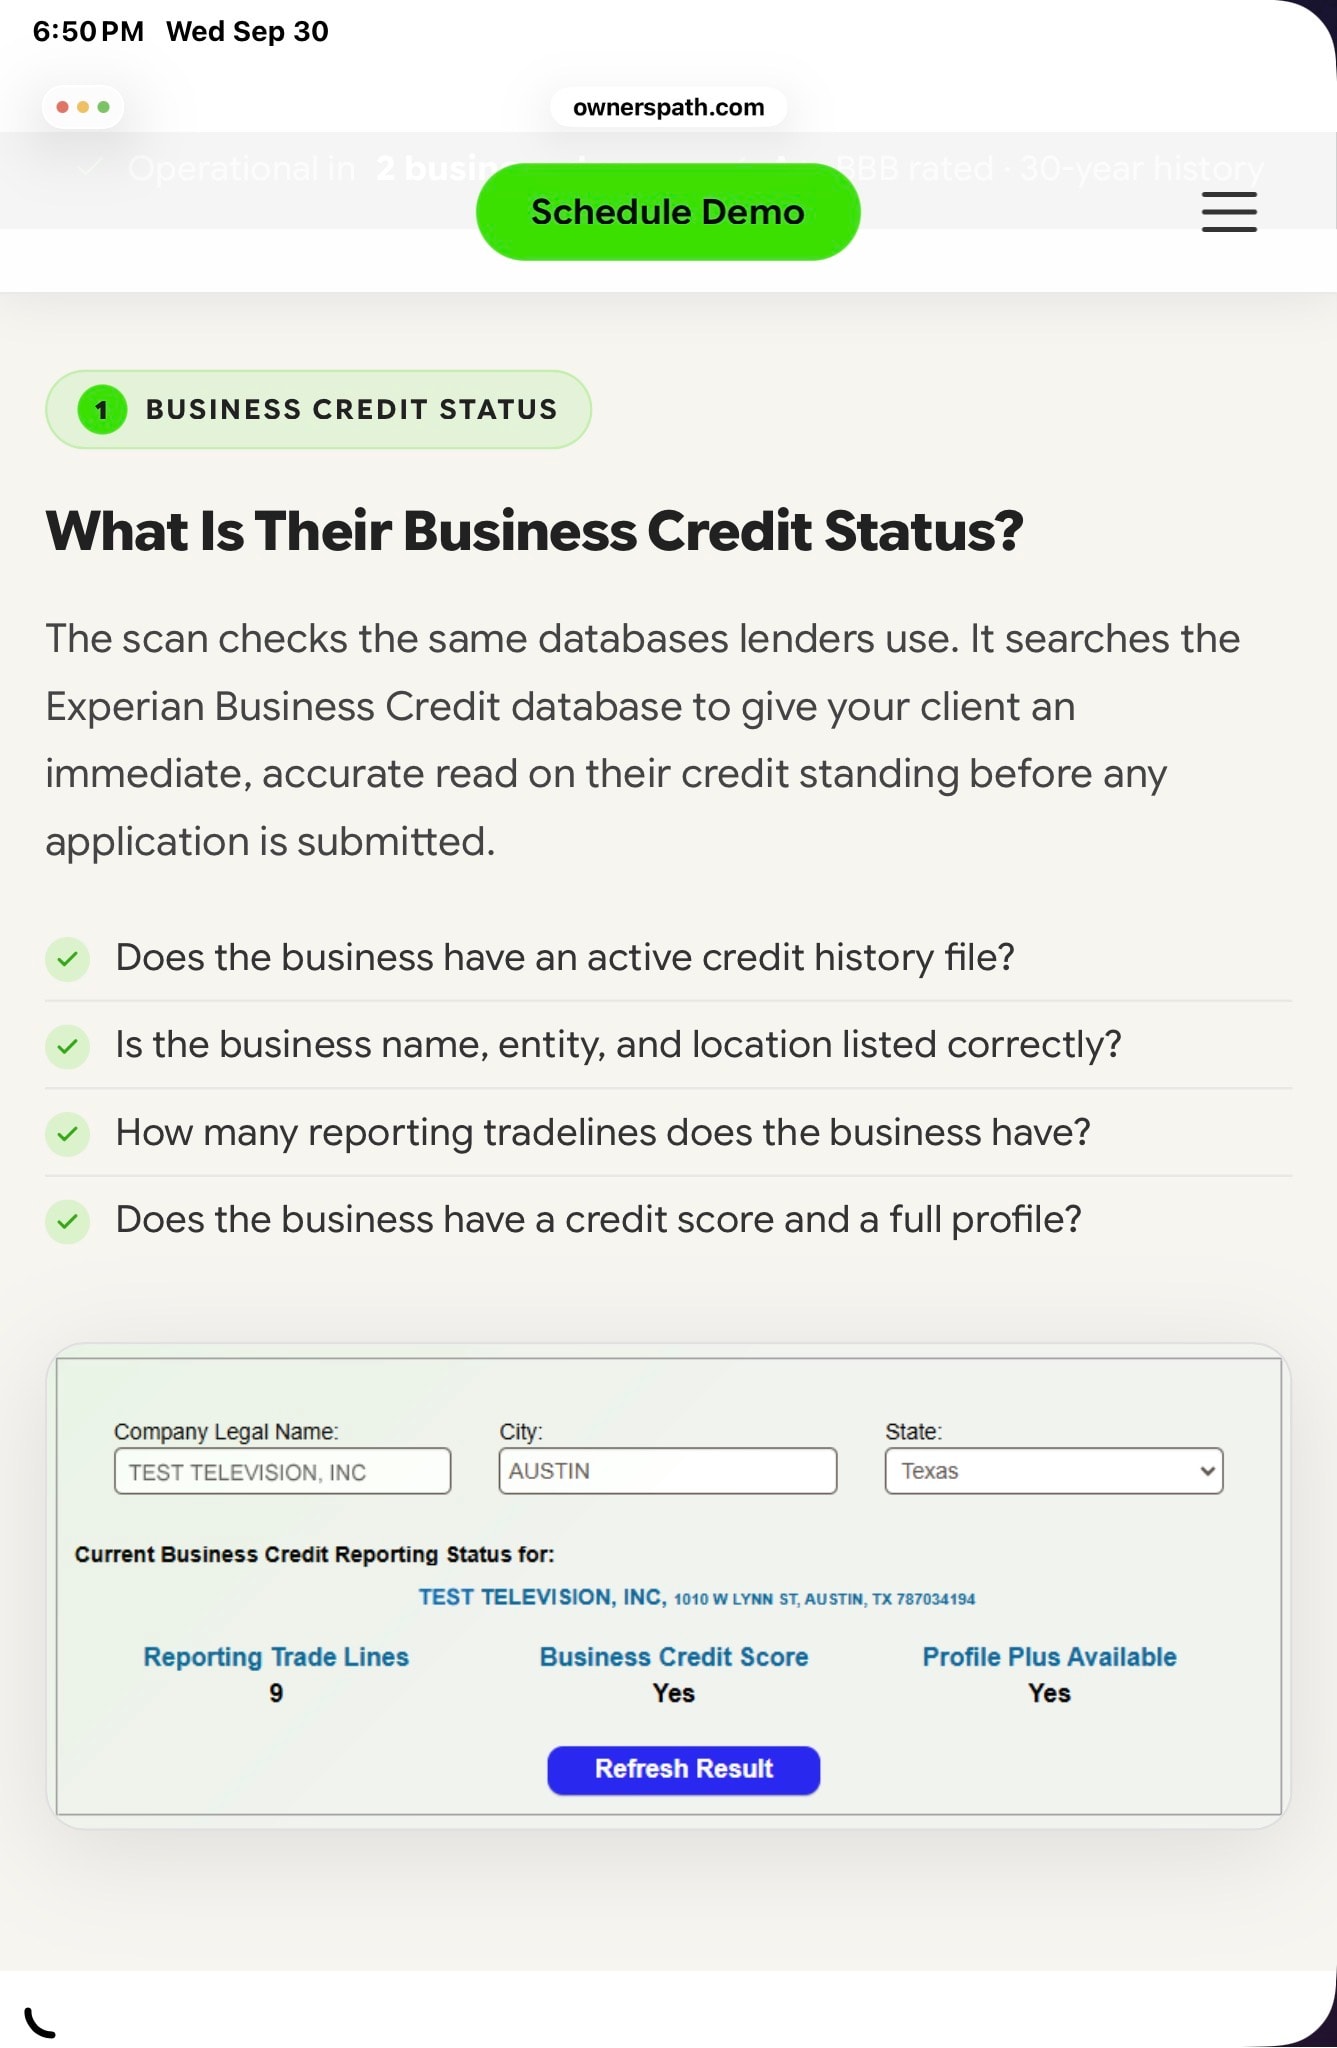
Not every funding program is right for every business. A 150-point business scan reviews your entity setup, credit profile, banking history, and lender compliance to identify which programs you're most likely to qualify for — so you apply with confidence, not guesswork.
Learn About the Business ScanLenders Check More Than Your Credit Score
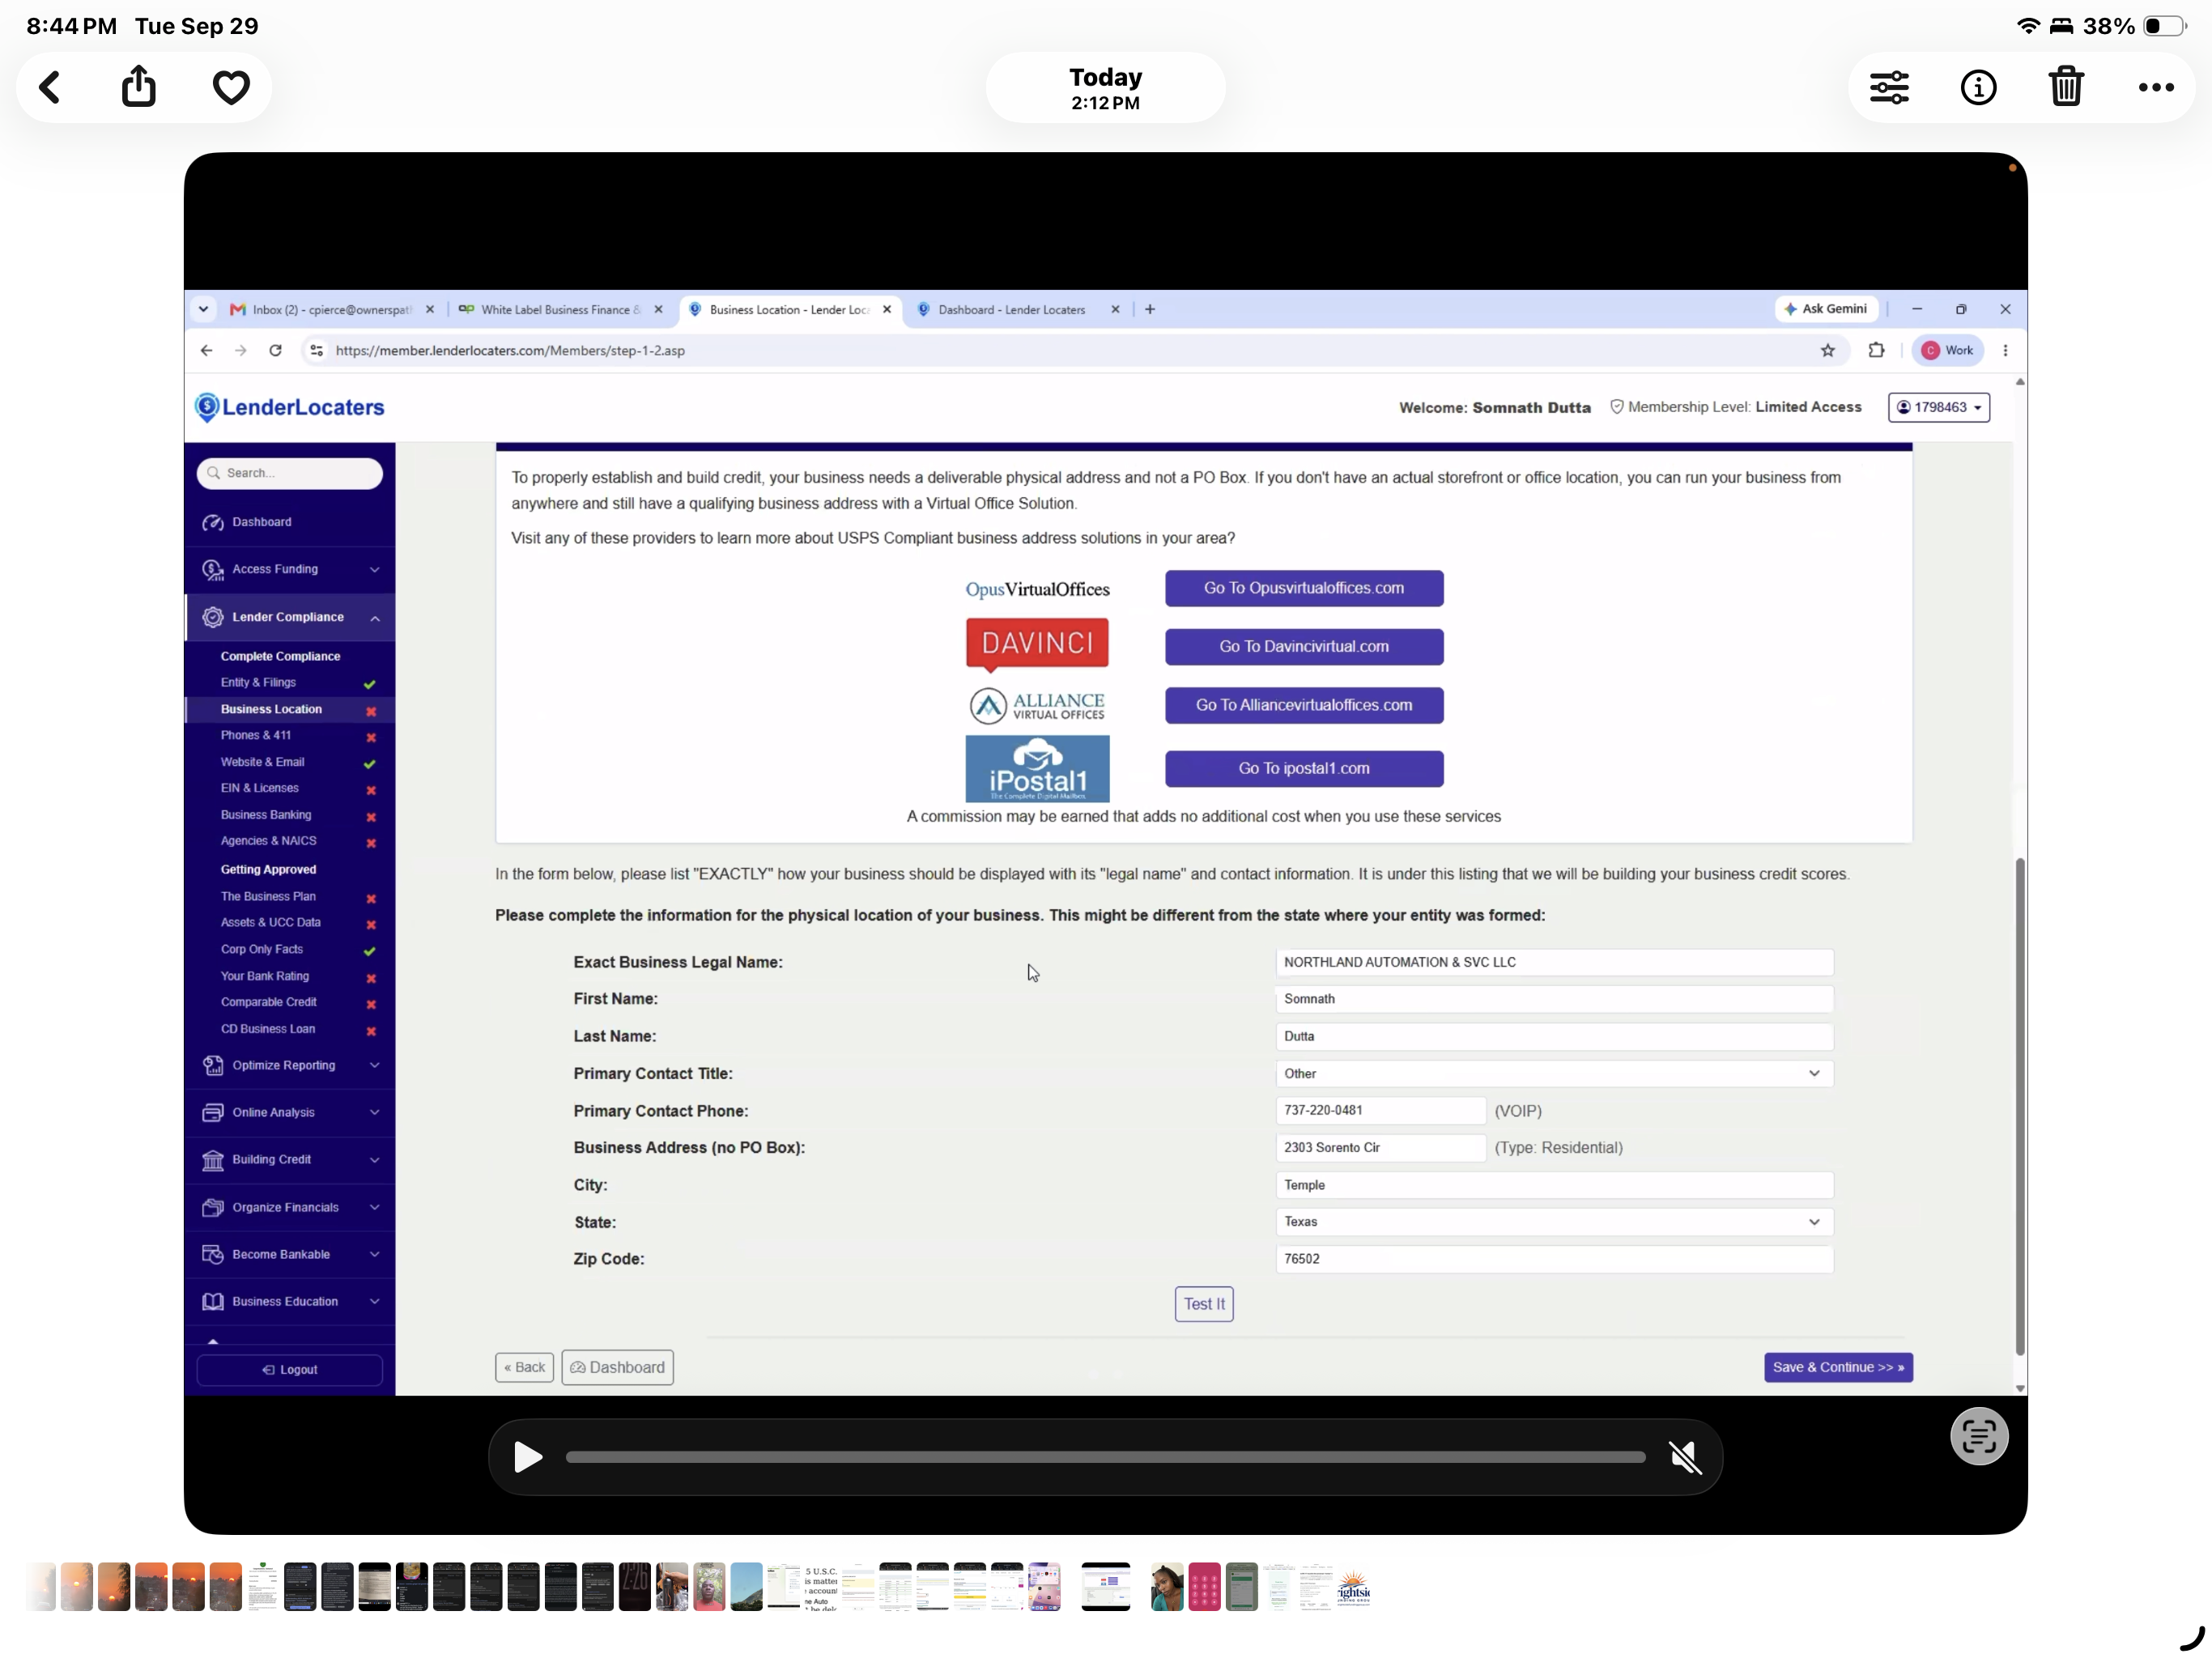
Before a lender approves your application, they run your business through a compliance checklist — verifying your entity structure, business address, phone listings, website, banking relationships, and more. Most businesses fail this check without knowing it.
- Entity structure and registration
- Business address and phone verification
- Banking history and account standing
- Business credit bureau profiles
- Online presence and directory listings
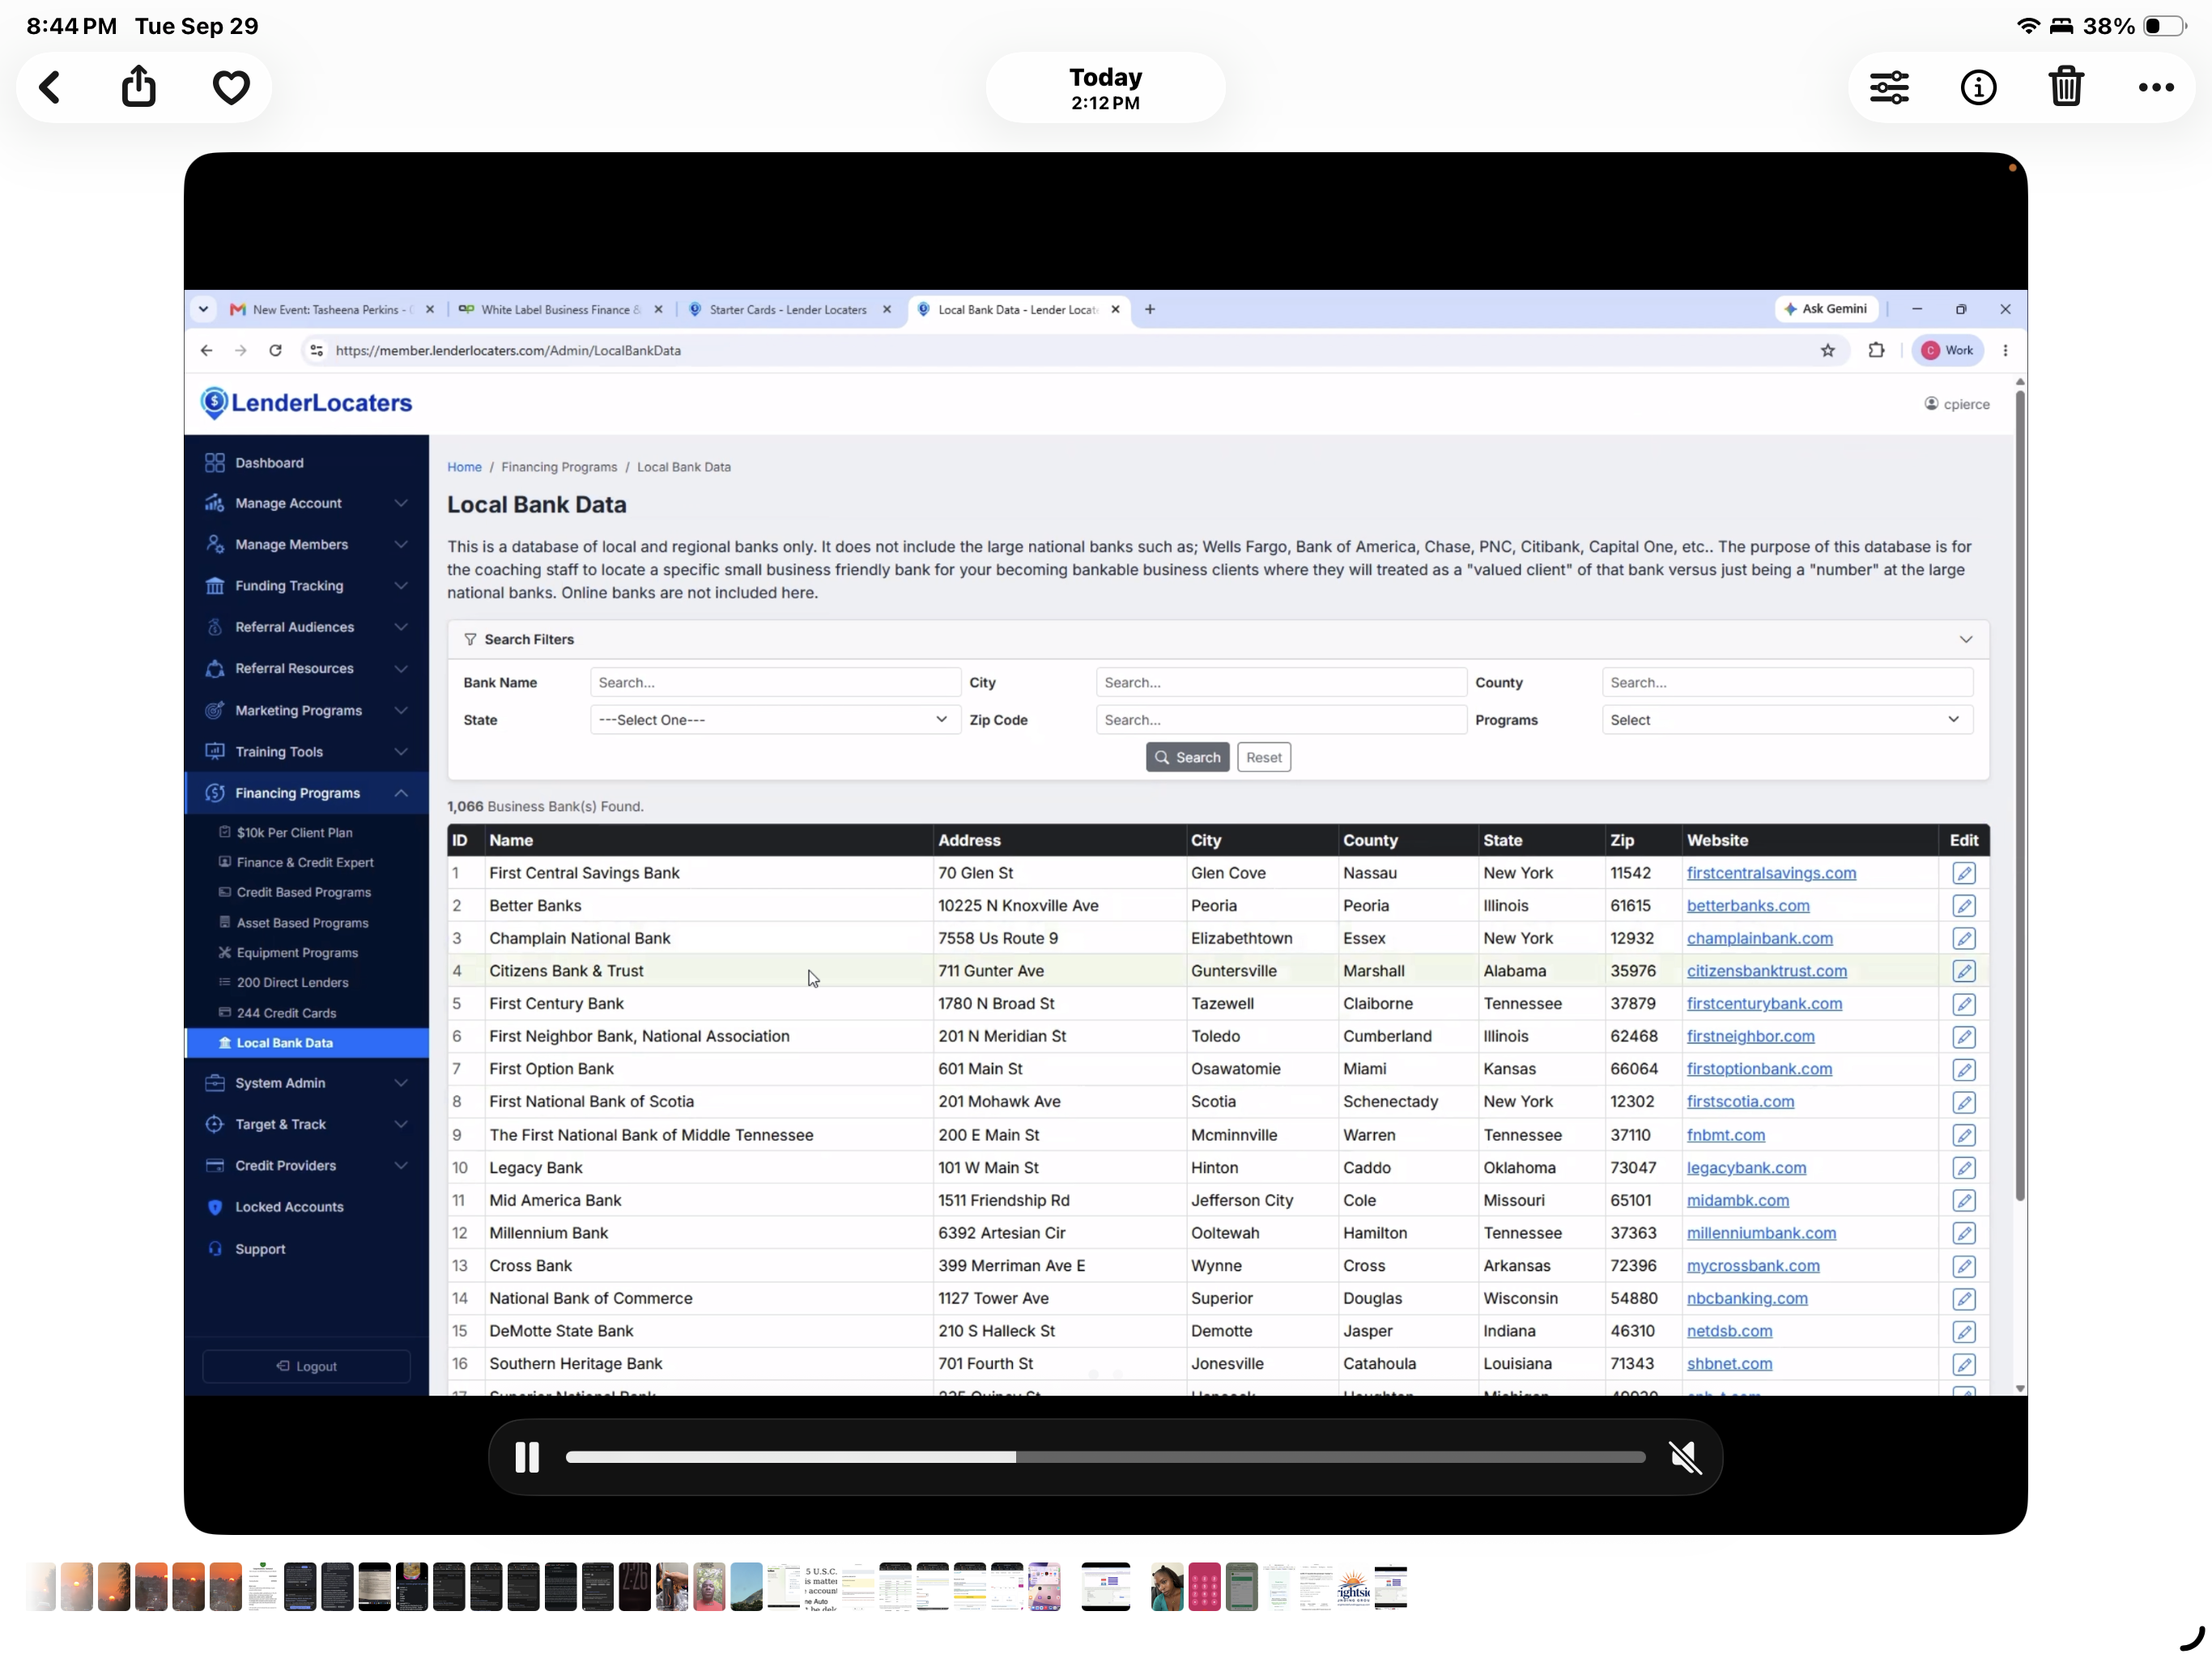
Access to Direct Lender and Funding Program Databases
Brightside puts 20+ funding programs, 200+ direct lenders, 240+ credit card approvals, and 3,000+ bankable vendor credit lines directly in your hands.
Over Twenty Business Funding Programs
Clients start with non-bankable programs on day one, then unlock better terms as they build toward bankable status.
- Non-bankable programs serve clients right away: revenue-based loans, merchant advances, receivables factoring, purchase order financing, asset-based lending, and more.
- Bankable programs open up once clients complete the credit-building process — better rates, longer terms, larger amounts.
More Than 200 Direct Business Lenders
Typically 10+ lenders per program, ranging from niche boutiques to national institutions.
- Smaller lenders accept submissions from brokers at any volume level, good for new clients still building their pipeline.
- Larger lenders require consistent monthly volume and fully packaged applications before approving — a goal to grow into.
Next Level: Over 3,000 Vendor Providers
Once clients achieve bankable status, a second database unlocks — and the terms are on a completely different level.
- Net-30 lines covering almost every product and service category, lines that can easily reach $500,000 or more.
- Large companies actively seek bankable clients — once clients get there, providers often reach out first.
Vendor Credit Line Providers
Revolving & Vendor Accounts
Hundreds of store and fleet revolving cards, plus net-30 vendor lines — all reporting to business credit bureaus to build your profile.
Net-30 vendor lines cover supplies, software, equipment, and services.
Match to the Right Program, Not Just Any Program
With 20+ funding programs across alternative, conventional, and SBA categories, the right match depends on your business profile — not just what's available.
Explore My OptionsWhat Lenders Review
Alternative Financing
Alternative financing options are often faster to access and have more flexible qualification standards than conventional loans. They typically carry higher costs and shorter repayment periods, making them better suited for short-term needs, cash flow gaps, or businesses that are still building their credit profile.
Conventional financing offers lower costs and longer terms — but preparation is everything.
Conventional Financing
Conventional financing — including term loans, lines of credit, and equipment financing — typically offers lower costs and longer repayment terms than alternative options. Qualification standards are generally higher, and lenders will review your business credit, personal credit, financial history, and overall lender readiness.
SBA Financing
SBA loans are government-backed financing programs that reduce lender risk, enabling banks and credit unions to offer better terms to qualifying small businesses. SBA loans typically require strong lender readiness — including business credit, financial documentation, and compliance — and involve a more thorough application process.
Important Note
Brightside Funding Group is not a lender. All financing options described here are provided for educational purposes. Availability, terms, rates, and qualification requirements are determined by individual lenders and programs and may change at any time. Nothing on this page constitutes a guarantee of financing or specific terms.
Not Sure Where to Start?
Understanding your options is the first step. Let's talk about where your business stands today and which financing paths make the most sense for your goals.
Explore My Funding Options